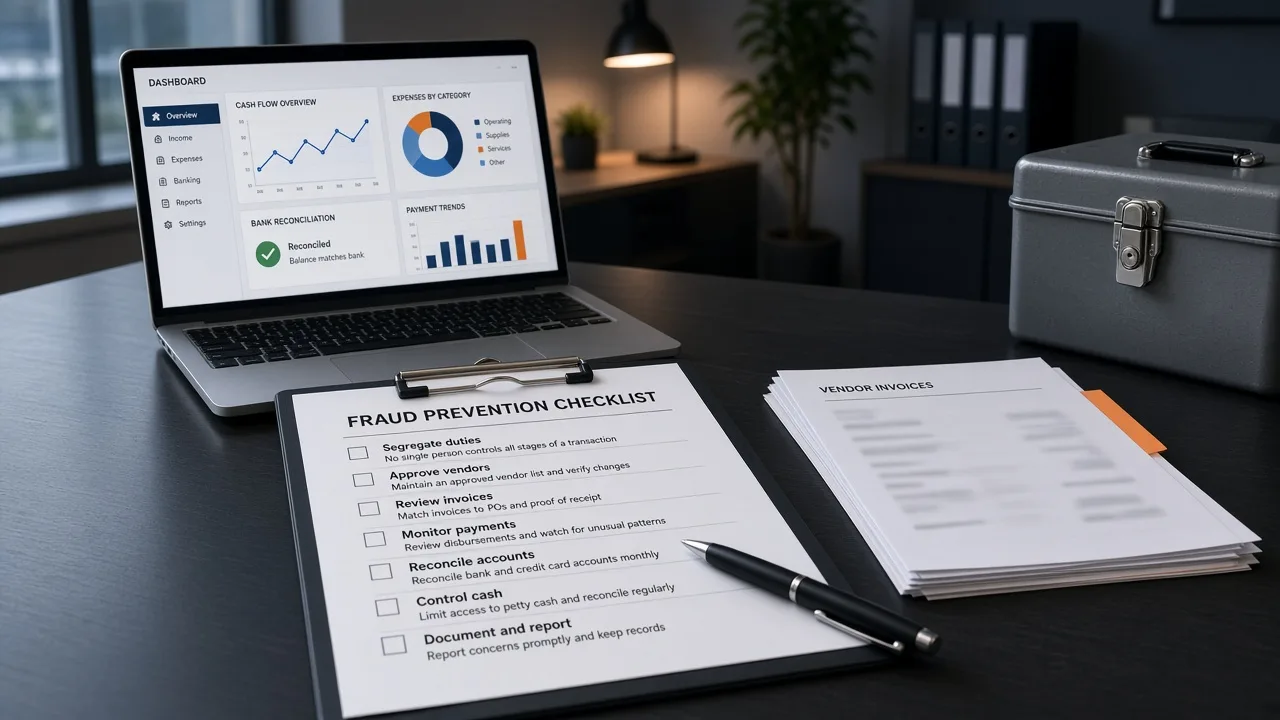
A fraud prevention checklist for Ontario business owners covers approvals, vendor controls, payroll hygiene, inventory checkpoints, and escalation paths when numbers look wrong. Use it to harden operations before losses grow. If you already suspect active embezzlement, move from checklist mode to corporate fraud investigations.
This fraud prevention checklist for Ontario business owners is built for SMEs that need practical controls—not a generic fraud encyclopedia.
Most small and mid-sized companies do not need a theatrical fraud program. They need a short list of controls that owners actually enforce. This post is that list. It is written for operators, not for auditors looking for a framework brand name.
It is also not an insurance claim fraud primer. Claim-side issues belong under insurance fraud services. Here, the business itself is the potential victim of internal or vendor schemes.
Why prevention checklists fail in real companies
They fail when only the bookkeeper sees the bank, when owners sign stacks of cheques without matching invoices, and when trusted staff hold every password. Trust is not a control. Separation of duties is a control.
Ontario business owners who want a practical fraud prevention checklist should treat each item as a weekly or monthly habit, not a policy PDF nobody reads. Licensed investigators at Investigation Hotline see the same breakdowns repeatedly: sole control of vendor master files, unreviewed expense accounts, and inventory counts that never reconcile to sales. Prevention does not require inventing statistics. It requires making theft harder and detection earlier. When prevention is too late, court-usable documentation from a formal investigation becomes the next tool. A confidential consult can help you decide which side of that line you are on.
Banking and payment controls
- Two-person approval for new vendors and bank detail changes
- Owner or controller reviews bank feeds weekly, not only month-end
- No shared banking logins among staff
- Out-of-band verification for large wire requests that arrive by email
- Reconcile Interac and credit-card statements to source receipts
Vendor and purchasing checklist
- Match purchase order, receiving record, and invoice before payment
- Flag vendors sharing addresses or phone numbers with employees
- Rotate who can create vendors versus who can approve payables
- Review top twenty vendors quarterly for rate creep and duplicates
- Require original invoices, not photo-only attachments, above a set threshold
Payroll and contractor hygiene
- HR or owner approves new hires and rate changes, not only payroll clerks
- Compare headcount to badge or scheduling systems monthly
- Watch for ghost employees, duplicate bank accounts, and sudden overtime spikes
- Contractors should not approve their own invoices end to end
Payroll schemes often hide in familiarity. The person who “has always done payroll” needs a backup reviewer who actually looks at exceptions.
Inventory and cash businesses
If you sell physical goods, count high-value SKUs on a surprise cadence. If you run cash sites, camera coverage and till variance reviews matter more than another binder of rules. Collusion between receiving and sales staff is a classic gap. Split those roles where headcount allows.
- Surprise counts on high-theft categories
- Camera retention long enough to investigate variances
- Separate receiving from invoice approval
- Investigate shrink concentrated on one shift or location
What early warning signs mean it is time to investigate
- Unexplained inventory shrink concentrated on one shift
- Vendor complaints about unpaid invoices the ledger shows paid
- Lifestyle changes in a staff member who controls money
- Accounting delays that always have a soft excuse
- Resistance to handing over system access during vacation
When two or more signs appear, stop quietly expanding the checklist and speak with counsel about a scoped investigation. Prevention tips do not replace fact-finding once a scheme is live. See also workplace investigation if the issue is misconduct without a clear money trail, and keep insurance claim matters on the insurance fraud lane.
Owner calendar: a simple monthly rhythm
- Week 1: bank and credit review
- Week 2: vendor change log review
- Week 3: payroll exception review
- Week 4: inventory or cash variance review
Ninety minutes a month beats a six-figure surprise. Assign a backup reviewer so one illness does not restore single-person control.
How investigators use prevention failures
When Investigation Hotline is retained on corporate fraud files, the first questions often map to this checklist: who could create vendors, who saw the bank, who counted stock. Strong prevention leaves fewer blind spots. Weak prevention still leaves a trail if you act before evidence is wiped.
Business owners building fraud prevention habits in Ontario should document control changes the same way they document other operational decisions. Dated notes about who held access, when duties were separated, and what exceptions were approved help later investigations and insurance conversations. Licensed private investigators rely on that operational history when reconstructing schemes. Court-usable documentation is easier to build when the company already kept clean approval logs. Prevention and investigation are sequential tools in the same risk system, not competing philosophies.
What not to do after you find a red flag
Do not send a company-wide email announcing an investigation. Do not confront the suspect alone in a parking lot. Do not seize personal phones without legal advice. Preserve access carefully, limit the circle who knows, and call counsel. Amateur steps can destroy evidence and create employment claims that distract from the fraud itself.
Expense accounts and corporate cards
Require itemized receipts, not summaries. Review merchant category outliers monthly. Disable cards the day employment ends. Watch for personal spending patterns that staff rationalize as temporary. Small leaks become culture.
- Cardholder agreements signed and retained
- Monthly exception reports reviewed by someone other than the cardholder
- Immediate cut-off on termination or leave
IT access as a fraud control
Finance systems, email, and cloud drives are fraud tools when access is forever. Remove leavers the same day. Review admin privileges quarterly. Log who can change vendor banking details. Technical access is part of the prevention checklist, not only an IT hygiene topic.
When access logs later become evidence in a corporate fraud investigation, clean offboarding history makes timelines easier to reconstruct. Prevention and investigation share the same audit trail. Ontario owners who keep that trail give counsel and licensed investigators a head start if escalation becomes necessary.
Document every control change with a date and owner. If a scheme later appears, those notes show whether prevention gaps were known and ignored or newly exploited.
Vendor master file discipline
The vendor master is where many Ontario SME frauds begin. Restrict who can create or edit vendors. Require dual approval for bank detail changes. Review new vendors weekly for the first ninety days. Compare vendor addresses to employee addresses.
If your accounting system cannot enforce dual control, compensate with manual dual sign-off and retain the emails. Weak systems are not an excuse for zero control.
- New vendor report every week
- Bank change report every week
- Quarterly scrub of dormant vendors
Culture signals owners should not ignore
Staff who never take vacation, who refuse cross-training, or who become aggressive when questioned about process often sit on fragile control points. That does not prove fraud. It does prove concentration risk. Force backup coverage and watch what breaks.
Prevention is partly mechanical and partly cultural. Owners who only buy software and never review exceptions still leave the door open. When exceptions pile up, escalate to corporate fraud investigation rather than rewriting the checklist again.
Board and owner reporting cadence
Even in small companies, someone other than the day-to-day bookkeeper should see exception reports. Owners who only review annual financials learn about fraud late. Monthly exception review is the practical middle.
- Bank exceptions
- Vendor changes
- Payroll outliers
- Inventory or cash variances
Put those four reports on a recurring calendar invite. When two turn red in the same month, call counsel about investigation options under the corporate fraud hub.
When prevention becomes investigation
Prevention ends when you have specific suspected transactions, suspects, or missing assets. At that point, preserve access, limit tip-offs, and contact counsel about a corporate fraud investigation. Continuing to tweak checklists while a live scheme runs is how losses compound.
Print the monthly rhythm, assign backups, and escalate early when red flags cluster. Prevention is a habit. Investigation is the escalation path when habit is no longer enough for an Ontario business that has already seen two or more warning signs in the same quarter. Do not wait for year-end statements to confirm what monthly exceptions already show.
Get help if the checklist already failed
If your review turned up active suspicion, contact Investigation Hotline at +1 416-205-9114 or via the contact page. Ask for corporate fraud investigations support, not a longer PDF of tips.
To learn more, contact Investigation Hotline at